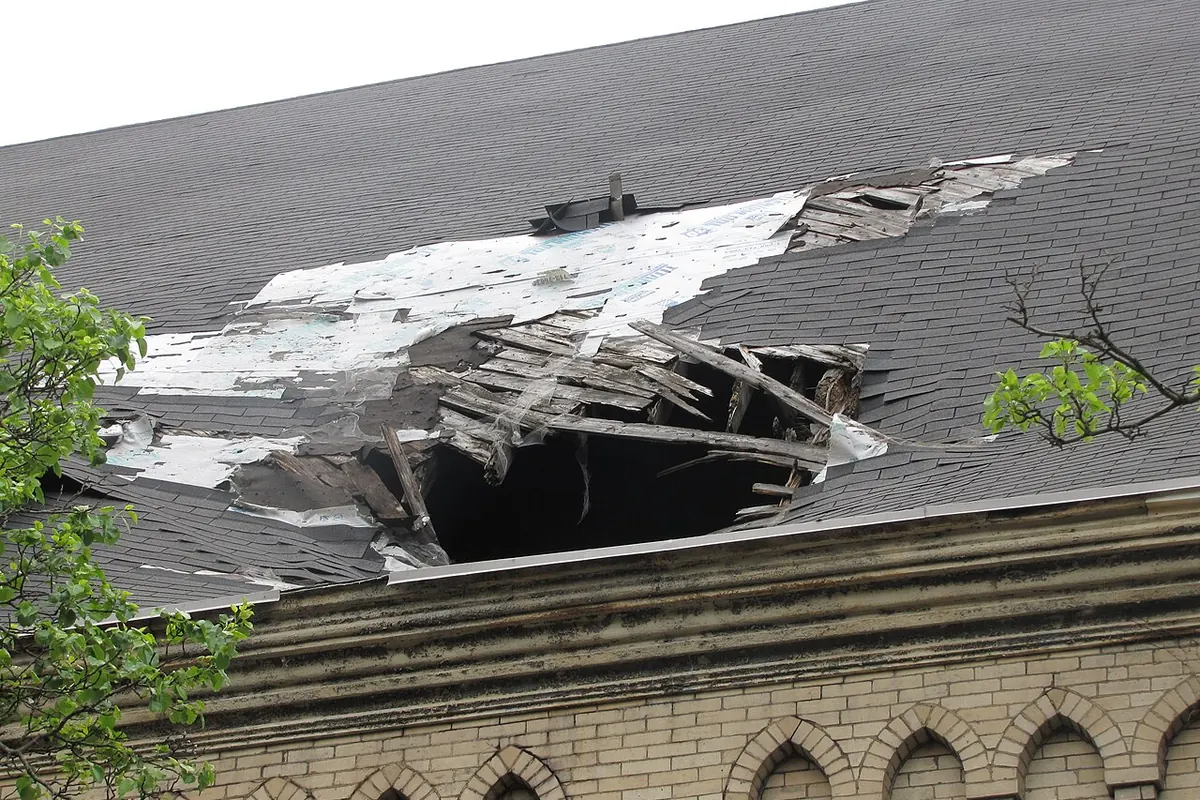
How roof and hail damage appraisal in SC works
Roof and hail damage appraisal in SC is for claims where the insurer agrees the roof was damaged by a covered storm but disagrees on how much repair is needed. It is the most common type of residential appraisal we handle, partly because roofs are expensive and partly because there is so much room for honest disagreement about repair versus replacement.
Spring hail is most frequent in the Upstate and Midlands, from Anderson and Greenville down through Lexington and Sumter, but strong summer thunderstorms bring hail statewide. Along the coast, roofs more often fail from wind, which is covered on our wind and tornado claim appraisal page.
What we measure and document
- Every slope, ridge, hip and valley, with pitch measured on site.
- Hail hits per test square on each slope, plus collateral damage on vents, gutters, downspouts, screens and HVAC fins.
- The shingle brand, line and exposure, to check whether matching material is still sold.
- Layers, decking type and fastening, which affect tear-off and code costs.
- Flashing, step flashing and chimney work that must be redone with any replacement.
For a quick sense of size before we visit, try the roof area and pitch estimator.
Common roof estimate disputes
Repair versus replacement
A carrier may approve a handful of shingles per slope while hail has bruised mats across the whole roof. Bruising can be hard to see from the ground and requires hands-on testing.
Matching and discontinued shingles
Many three-tab and early architectural lines are no longer made. When replacement shingles won’t match in color or dimension, a spot repair can leave a visibly patched roof. How matching is handled depends on policy wording.
Code and steep or high charges
Drip edge, ice and water barrier in valleys, decking re-nailing and permits can be required on replacement. Steep pitches and two-story eaves need extra labor and safety equipment, and those charges are often missing from first estimates.
Cosmetic damage on metal roofs
Standing-seam and exposed-fastener metal roofs are popular in the Lowcountry and on rural homes. Some policies carry a cosmetic damage exclusion for dents that don’t affect function, which can limit what appraisal can address.
Documentation that strengthens a roof appraisal
Keep the date of the storm, local hail reports or news coverage, close-up photos with a coin or tape measure for scale, photos of dented gutters, car hoods or patio furniture, any prior roof inspection or installation invoice, and every carrier estimate including the measurement report.
How a roof panel usually unfolds
Roof appraisals often turn on a joint inspection. When both appraisers walk the roof together, count hits per test square and look at the same shingles, many disagreements disappear. What is left tends to be matching, code items and pricing, which are easier to resolve with product information, local permit requirements and current supplier quotes. Upstate subdivisions built in the same few years often share shingle lines, which can make matching evidence easier to gather.
When roof appraisal isn’t the right tool
If the insurer says the roof leaked for years or that the damage is purely from age, the issue is causation and coverage, and an appraisal panel may not be the right place to decide it. The same is true if the policy has a cosmetic exclusion or an actual cash value roof schedule that limits payment by roof age. In those cases a South Carolina attorney can explain your options, and we will tell you up front if we think appraisal won’t change the outcome.
Questions about roof & hail damage appraisal
How do I know if my roof has hail damage?
Look for dented gutters, vents and screens, then have a qualified inspector check shingles by hand for soft bruises. Photos with a scale reference taken soon after the storm are the best record.
Will appraisal get me a full roof replacement?
No one can promise that. The panel decides what the covered damage costs to repair, and in some cases that is a full replacement and in others it is a repair.
Does my roof’s age affect the payment?
It can. Some policies pay actual cash value on older roofs, or use a roof payment schedule, which reduces payment based on age regardless of appraisal.