Local claim risks
- Hurricane wind
- Storm surge (flood policy)
- River flooding
- Wind-driven rain
- Mold after water losses
Housing mix
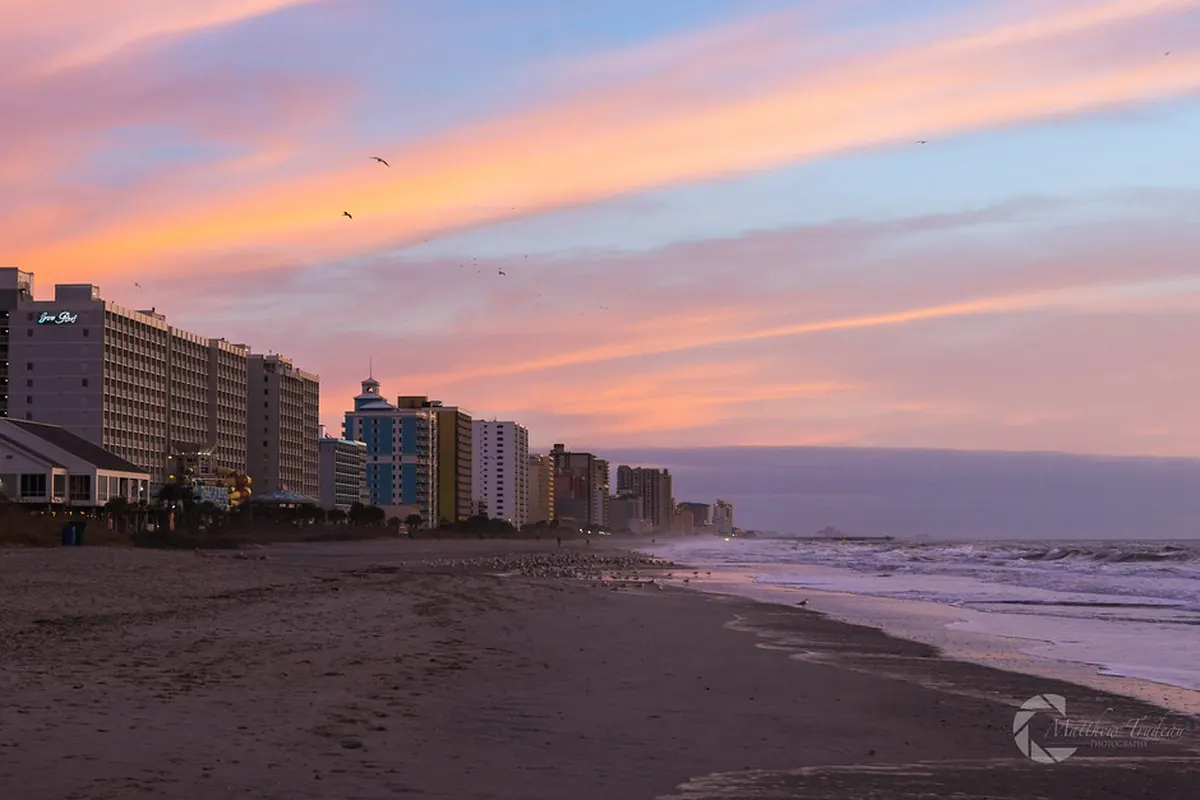
Oceanfront high-rise and mid-rise condominiums line the beach, backed by older cottages and motels, golf-course communities and large newer subdivisions in Carolina Forest and along the Waccamaw.
Storm history
- 1954 · Hurricane Hazel — devastated the Grand Strand, destroying many oceanfront buildings
- 2016 · Hurricane Matthew — wind damage and inland river flooding in Horry County
- 2018 · Hurricane Florence — record Waccamaw River flooding around Conway and Socastee
- 2022 · Hurricane Ian — landfall near Georgetown; surge and wind damage along the Strand
Neighborhoods we cover
Market Common, Carolina Forest, Pine Lakes, Socastee, Surfside Beach, North Myrtle Beach, Murrells Inlet
Why Grand Strand claims have more moving parts
A single hurricane claim in Myrtle Beach can involve four policies. An oceanfront condo owner might have an HO-6 unit policy, rely on the association’s master policy for the building, carry a wind and hail policy through the South Carolina Wind and Hail Underwriting Association, and hold flood insurance through the NFIP or a private carrier. Each policy has its own deductible, its own definitions and its own adjuster. Before anyone argues about price, someone has to work out which policy pays for which piece.
The housing itself adds complexity. High-rise towers along Ocean Boulevard have commercial roofing, balcony assemblies, storefront glazing and shared mechanical systems. Inland, Carolina Forest and Socastee are mostly newer wood-frame homes with vinyl siding and asphalt roofs. Golf communities around Pine Lakes and Market Common sit somewhere in between. Rental and second-home properties also raise questions about vacancy, loss of rents and who discovered the damage and when.
How the storm record shapes claims today
Hurricane Hazel in October 1954 remains the benchmark for the Grand Strand; it wiped out much of the oceanfront that existed at the time. More recent storms have been less dramatic on the beach but costly inland. Matthew in 2016 and especially Florence in 2018 sent rivers out of their banks for days after the rain stopped, and the Waccamaw flooding around Conway and Socastee damaged homes that had never flooded before. Many of those owners had no flood policy.
Hurricane Ian came ashore near Georgetown in September 2022, bringing surge and wind damage to piers and oceanfront property along the Strand. Ian claims are a good example of the wind-versus-water split: surge damage on lower floors belongs to the flood carrier, while roof, window and balcony damage from wind belongs to the wind or homeowners carrier. Our wind and flood damage splitter can help you think through that division before a claim is negotiated.
Estimate disputes common on the Grand Strand
- Master policy versus unit policy. Association bylaws and the master policy decide whether cabinets, flooring and fixtures in a unit belong to the building or the owner.
- Hurricane deductibles. Percentage deductibles on high coverage limits can absorb a large share of a loss, and the trigger language varies.
- Wind-driven rain versus surge. Water inside a unit may have come through a failed slider or roof, or from rising water, and each answer points to a different policy.
- Commercial roofing and balconies. Pricing for towers depends on access, staging and specialty contractors, all of which first estimates often understate.
- Mold after delayed discovery. Second homes may sit for days before anyone sees the damage, which invites arguments about mold and mitigation limits.
Documentation advice and how we work locally
If you own a rental or second home, arrange for someone to check it promptly after a storm and photograph every room, the balcony, sliders and any water lines. Request a copy of the association’s master policy and the bylaws section on insurance responsibilities. Keep a list of contacts for every policy and note claim numbers for each one.
We inspect in person, review the policies that apply and write an independent estimate. For associations, our commercial and HOA appraisal work covers building-wide losses. Appraisal settles the amount of loss; it does not decide coverage, so if a carrier has denied part of the claim outright, talk with a South Carolina attorney.
Services in Myrtle Beach
Every South Carolina Insurance Appraiser service is available in Myrtle Beach and the surrounding area, including:
- Appraisal Demand Representation
- Home Insurance Appraisal
- Commercial & HOA Appraisal
- Roof & Hail Damage Appraisal
- Wind & Tornado Claim Appraisal
- Hurricane Claim Appraisal
- Water Damage Claim Appraisal
- Fire & Smoke Damage Appraisal
Myrtle Beach claim questions
My condo association and I both have insurance. Who covers my unit’s floors and cabinets?
That depends on the master policy and the association’s governing documents. Some cover original finishes; others leave everything inside the unit walls to the owner’s HO-6. We review both before valuing your portion.
My Carolina Forest home flooded from the river. Will my homeowners policy pay?
Generally, river and surface flooding are covered only by a flood policy. Your homeowners policy may still cover other damage, such as wind damage to the roof. A South Carolina attorney can advise if coverage is disputed.
Can appraisal be used on a South Carolina wind pool claim?
Wind and hail policies often have their own appraisal provisions. We read the policy language first, then advise whether appraisal fits the disagreement you have.