Why the split matters on the coast
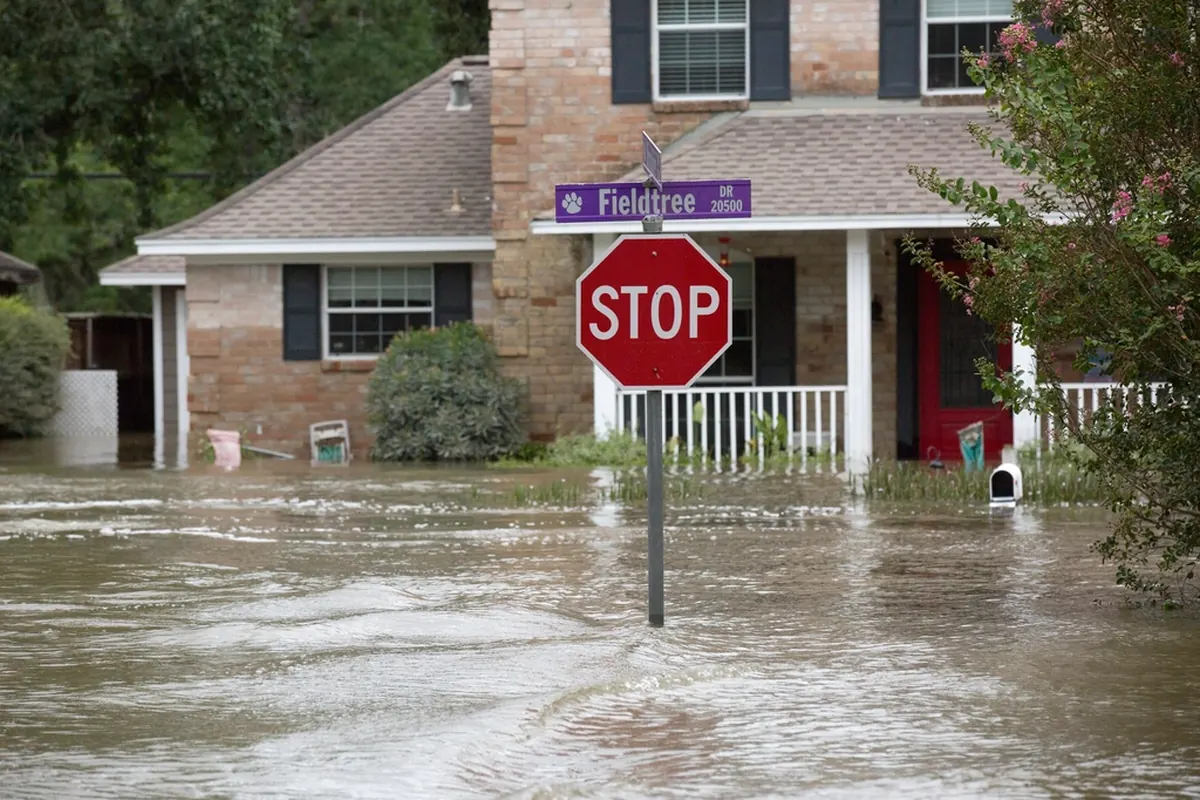
Homeowners and SCWHUA wind policies exclude flood; flood policies exclude wind. When Hugo, Matthew or Ian drove water into homes that also lost shingles and windows, each carrier valued only its own share, and every point of the split moved real money. This calculator lets you see how sensitive your recovery is to that allocation, using illustrative numbers you control.
How the math works
- The wind share of the total is reduced by your hurricane deductible (a percentage of the dwelling limit).
- The water share is reduced by the flood deductible and capped at the flood building limit.
- Whatever neither policy pays is your shortfall.
Where appraisal fits
Appraisal under the wind policy can settle the amount of wind damage, but whether a given item was caused by wind or water can be treated as a causation or coverage question. Flood policies have their own claim and appraisal rules. Good documentation — water lines, interior photos, debris lines, roof and window damage — is what supports a fair split. See our guide to wind pool claims and appraisal.
Questions about this tool
Is the wind percentage something I decide?
No. The split is determined from evidence by the adjusters, appraisers or, if disputed, others. The slider just shows how sensitive your recovery is to it.
Does this include contents?
No. It models building damage only. Contents have separate limits and deductible rules on both policies.