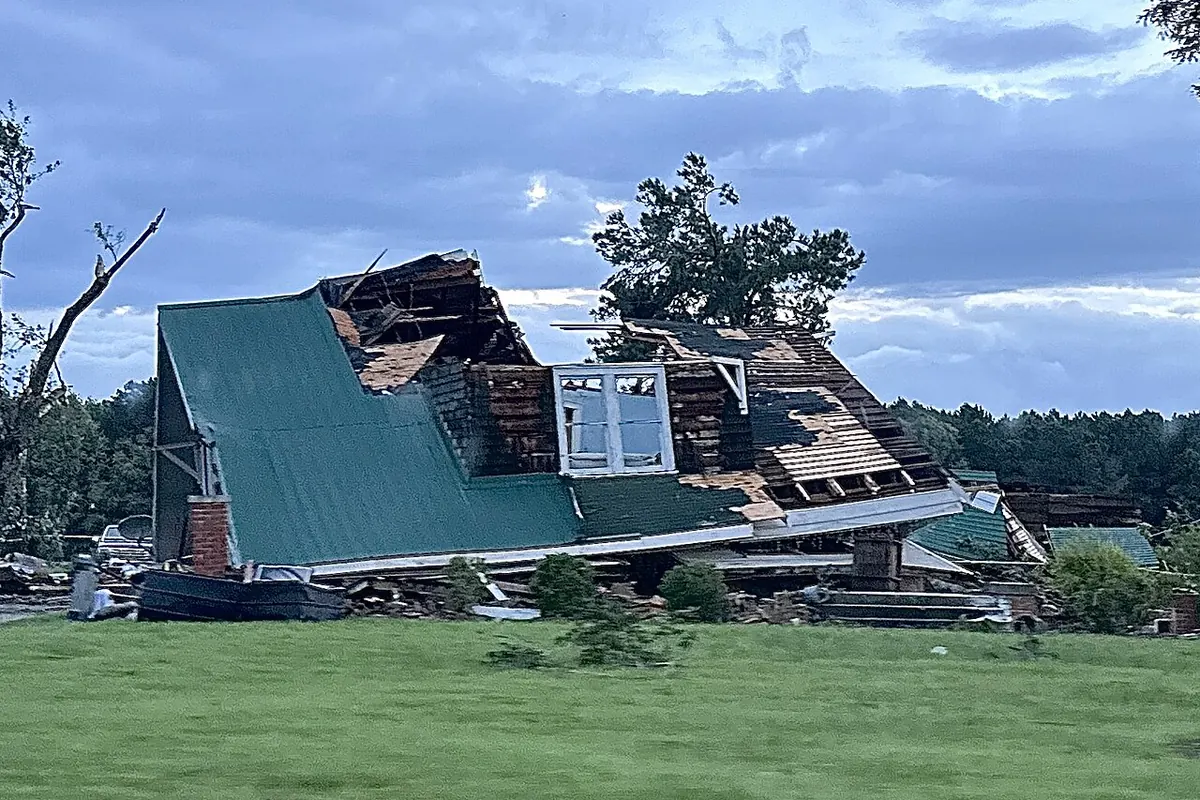
Wind and tornado claim appraisal in SC, explained
Wind and tornado claim appraisal in SC applies when the insurer accepts that wind caused damage but pays less than the repair costs. Straight-line winds from summer thunderstorms, gusts from tropical systems moving inland, and tornadoes can all leave damage that is widespread but uneven, which makes it easy for an estimate to overlook whole areas.
Tornadoes are not just a Midwestern problem. The April 13, 2020 Easter outbreak produced an EF3 tornado in Seneca and Oconee County and strong tornadoes in Hampton County, and tropical systems regularly spin up brief tornadoes across the Midlands and Pee Dee.
What wind damage typically includes
- Lifted, creased or missing shingles, often on windward slopes and along rakes and ridges.
- Vinyl siding torn off or cracked, plus damaged soffit, fascia and gutters.
- Broken windows, screens, doors and garage doors.
- Fences, carports, sheds and screened porches.
- Interior ceiling and wall damage from rain entering through the openings the wind created.
- Structural movement in framing, porches or chimneys after a tornado.
Common estimate disputes on wind claims
Spot repairs on brittle roofs
A carrier may approve replacing a few shingles, but older shingles often break when crews try to lift them for a repair. Whether a repair can be done without damaging surrounding shingles is a frequent panel topic.
Siding that can’t be matched
Vinyl siding fades and profiles change over the years. Replacing one wall with a new color can leave a home with mismatched elevations, and the treatment of matching depends on the policy.
Interior water from wind-driven rain
Many policies cover rain that enters through an opening created by wind, but not rain that seeps in through an intact roof. The order of events matters, so photos of the opening and the interior stains are important.
Hurricane or named-storm deductibles
A strong thunderstorm is not a hurricane, but a tornado spawned by a tropical system might trigger a percentage deductible depending on wording and timing. Check our hurricane deductible calculator to see how a percentage deductible changes the payment.
South Carolina homes and wind
Rural manufactured homes, Upstate mill houses with older framing and vinyl-sided subdivision homes in York and Lancaster counties all respond to wind differently. Manufactured homes may need tie-down and skirting work; older houses may need repairs that bring wiring or framing up to current code. Large pines and oaks add tree damage to many wind claims, which we address on our tree fall page.
Documentation that helps
Note the date and time of the storm and save any National Weather Service warnings or local news reports. Photograph every elevation, the roof if it can be done safely, debris in the yard, and interior damage as it appears, before cleanup. Keep receipts for tarps, board-up and water extraction, since reasonable emergency repairs are usually part of the claim.
How the panel handles a wind claim
We walk every elevation with the other appraiser where possible and agree on which areas were damaged before talking about price. Once the scope is settled, the remaining issues are usually repair method and unit cost, which can be supported with manufacturer guidance and local bids.
When appraisal is not the answer for a wind claim
If the insurer says damage came from age, poor installation or a flood rather than wind, the dispute is partly about cause. Some panels can address causation within the amount of loss and some policies or courts limit that, so a South Carolina attorney is the right person to advise. Appraisal also isn’t the tool if the carrier has denied the claim for late reporting or a lapse in coverage.
Questions about wind & tornado claim appraisal
Is tornado damage covered by a standard homeowners policy?
Wind, including tornadoes, is usually a covered peril, but some coastal policies exclude wind and rely on a separate SCWHUA policy. Check your declarations page.
What if the insurer only paid for part of my roof?
If you believe the whole roof or slope needs replacement, appraisal can be used to resolve how much repair the covered damage requires.
Does a tornado trigger my hurricane deductible?
It depends on how the policy defines the deductible trigger. Read the definition carefully, and ask the SCDOI or a South Carolina attorney if the wording is unclear.