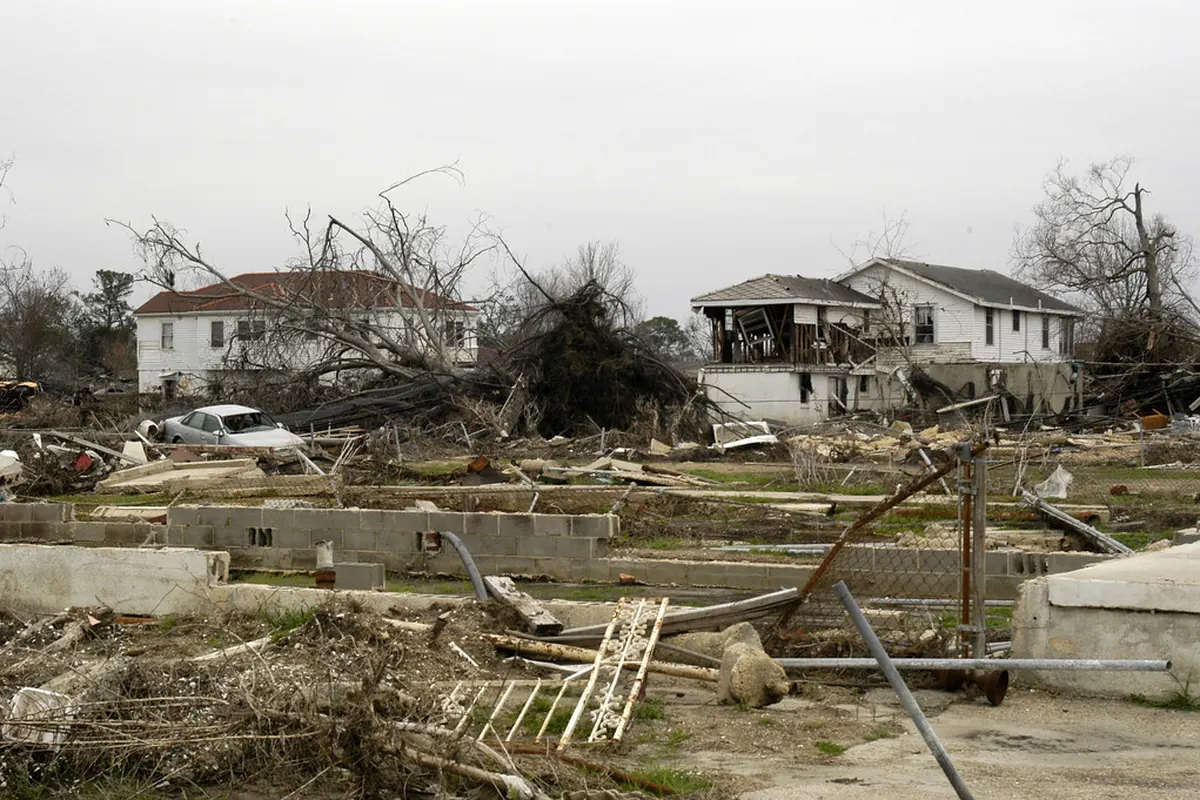
Why hurricane claim appraisal in South Carolina is different
Hurricane claim appraisal South Carolina property owners pursue usually starts with one question: which damage was caused by wind and which by water? Wind and wind-driven rain are typically covered by a homeowners or SCWHUA policy, while storm surge and rising water are flood, which needs a separate NFIP or private flood policy. That split shapes every estimate.
The state’s history shows how far hurricane damage can reach. Hugo came ashore near Sullivan’s Island in 1989 and still caused heavy damage in Sumter and the Midlands. Matthew in 2016 toppled thousands of trees on Hilton Head and around Beaufort. Florence in 2018 brought record river flooding to Conway and the Pee Dee, Ian made landfall near Georgetown in 2022, and Helene in 2024 hammered the Upstate and Aiken County with wind far from the coast.
SCWHUA, homeowners and flood policies
In designated coastal areas, many owners carry an SCWHUA policy for wind and hail alongside a homeowners policy that excludes wind, plus flood insurance. Each policy has its own deductible, its own adjuster and its own appraisal wording. An award under the wind policy does not bind the flood carrier, and the reverse is also true.
Our wind and flood damage splitter helps you sketch how damage might divide between policies before you talk to adjusters.
Common hurricane estimate disputes
- Wind versus surge. A waterline on interior walls does not mean every interior repair was flood. Roof openings and broken windows can let wind-driven rain into upper floors and ceilings.
- Hurricane deductible triggers. Whether a percentage deductible applies depends on how the policy defines the triggering storm and its time window. See our guide to hurricane deductibles explained.
- Post-storm pricing. Labor and materials spike after a major storm. An estimate priced at pre-storm rates may not reflect what contractors can actually charge in Horry, Charleston or Beaufort County months later.
- Elevated and historic homes. Raised coastal homes need lifts and extra access; Charleston single houses with piazzas, stucco and historic masonry need specialty trades and may face review board requirements.
- Code upgrades. Repairs to coastal homes can trigger current wind-load requirements for fastening, connectors and openings.
Documentation that matters after a hurricane
Take photos and video of every room and every elevation before cleanup, including waterlines, roof openings, missing shingles, broken windows and debris. Keep the timing straight: when the wind peaked, when water rose, and when you first saw interior leaks. Save mitigation invoices, generator and hotel receipts, and every letter from every carrier. If you made improvements through the SC Safe Home program, keep those records too.
How we approach a hurricane panel
We start by separating the scope into wind-related items, flood-related items and items that could be either. Only the wind side goes to the panel under a wind or homeowners policy. Being transparent about that split tends to build credibility with the other appraiser and keeps the award clean if a flood claim is still open.
When appraisal is not the right tool after a hurricane
If the dispute is mainly about whether damage was flood rather than wind, the question is coverage and causation, and an appraisal panel may have limited power to decide it. Disputes with an NFIP flood carrier follow their own federal process. And if a carrier has denied a claim entirely or is delaying without explanation, consider contacting the SCDOI or a South Carolina attorney. We are glad to give an honest view of whether appraisal will actually help.
Questions about hurricane claim appraisal
Can I appraise my SCWHUA wind claim separately from my flood claim?
Yes. Each policy is a separate contract with its own process. An appraisal under the wind policy only sets the amount owed under that policy.
What is a hurricane deductible?
It is a deductible, often a percentage of the dwelling limit, that applies when a defined hurricane or named storm causes the loss. The trigger and time window depend on your policy wording.
How soon after a hurricane should I document damage?
As soon as it is safe. Photos taken before cleanup and before temporary repairs are the strongest evidence of what the storm did.