Why this deductible catches people off guard
For many homeowners, the hurricane deductible in South Carolina policies is the single largest number on the declarations page, and it is easy to miss until a storm arrives. A standard deductible might be $1,000 or $2,500. A hurricane deductible is often a percentage of the dwelling limit, and on a coastal home that can mean five figures before the insurer pays anything.
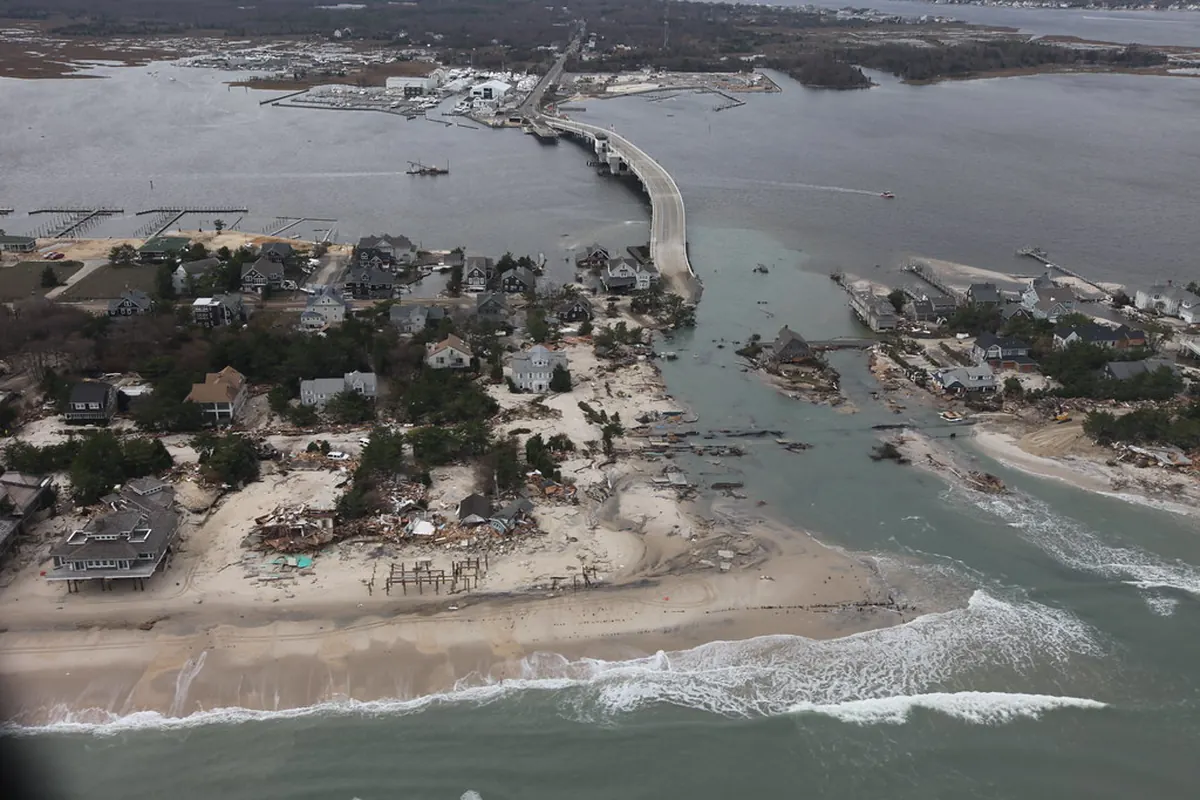
That gap shapes almost every storm claim along the coast, from Hilton Head Island and Beaufort to Charleston, Georgetown and the Grand Strand. It also matters inland. Hugo pushed damaging winds through Sumter and the Midlands in 1989, and Helene brought widespread tree fall to the Upstate and Aiken County in 2024. Whether a hurricane deductible applied to those inland losses came down to each policy’s wording.
What triggers it
There is no single statewide trigger. Each policy defines when its hurricane or named-storm deductible replaces the standard one. Common approaches include:
- Watch or warning triggers. The deductible applies to losses during a window that starts when the National Weather Service issues a hurricane watch or warning for any part of South Carolina and ends a set number of hours after it is lifted.
- Named-storm triggers. The deductible applies to any storm named by the National Hurricane Center, including tropical storms that never reach hurricane strength.
- Peril limits. Many forms apply the deductible only to wind and hail during the storm window. Fire from a lightning strike during the same storm may fall under the standard deductible.
Read the trigger language word for word. A storm like Matthew in 2016, which made landfall near McClellanville as a Category 1, or Ian in 2022, which came ashore near Georgetown, can produce very different deductible outcomes under two policies on the same street.
How the math works
A percentage deductible is calculated on the Coverage A dwelling limit, not on the amount of damage. That is the part most people get wrong.
Here are illustrative figures only. Say a Mount Pleasant home is insured for $450,000 under Coverage A with a 2% hurricane deductible. The deductible is $9,000. If the insurer values the wind damage at $11,500, the payment is $2,500. If your contractor’s estimate is $24,000, the payment would be $15,000. Same deductible, but the gap between the two estimates is now the whole claim.
The same arithmetic explains why small underpricing hurts so much on a coastal claim. A missing ridge vent, a short count on roof squares or no overhead and profit can push a claim from barely above the deductible to below it. You can test your own numbers with our hurricane deductible calculator.
Stacked deductibles
Homes in coastal areas that pair a South Carolina Wind and Hail Underwriting Association wind policy with a homeowners policy and a flood policy can face more than one deductible from one storm. Wind damage carries the wind policy’s hurricane deductible, water from storm surge carries the flood deductible, and an unrelated covered loss carries the homeowners deductible.
Disputes appraisal can help with
Appraisal decides the amount of a covered loss. It does not usually decide which deductible applies, because that is a question of policy interpretation. But the amount is often the real fight. Disputes that fit appraisal include:
- Whether the full roof slope or only a few shingles need replacement.
- Matching of siding, shingles or flooring that can’t be blended with existing materials.
- Steep and high-roof charges on the multi-story homes common in the Lowcountry.
- Code upgrades required by the local building department, such as drip edge, underlayment or roof-to-wall connections.
- Interior water damage from wind-driven rain after the roof was opened up.
When the insurer’s number sits just under the deductible, a careful line-by-line valuation can make the difference between no payment and a meaningful one. Our hurricane claim appraisal page explains how we approach those reviews.
Ways to soften the blow before the next storm
South Carolina’s 2007 coastal insurance reforms added a few tools worth knowing about. None of them is legal or tax advice, so confirm details with the program or a professional.
- Clear disclosure. Insurers must clearly disclose a hurricane deductible, so you should find the dollar or percentage amount on your declarations page. If it isn’t clear, ask your agent to state it in dollars.
- Catastrophe savings accounts. These tax-advantaged accounts let you set money aside for a hurricane deductible or other uninsured storm losses.
- SC Safe Home grants. Eligible homeowners can apply for help paying for wind-resistance upgrades, which may also qualify for insurance discounts.
It also pays to review your deductible choice at each renewal. A lower percentage costs more in premium, but on an older roof in Beaufort County it may be cheaper over time than absorbing a large share of the next storm yourself.
What to do after the storm
Photograph the damage before any cleanup, keep receipts for tarps and emergency repairs, and get a detailed written estimate from a contractor who itemizes quantities rather than giving a single lump sum. When the insurer’s estimate arrives, compare it with yours line by line, subtract the deductible from both, and look at what is actually in dispute. If the gap is large and the disagreement is about price and scope rather than coverage, appraisal may be the right next step.